Retirement Without A Permanent Address
For years, the retirement playbook was pretty straightforward: pay off the mortgage, retire, and stay in the house until someone carries you out.
But what if the house you worked so hard to own is actually limiting one of the best things retirement can give you?
Freedom.
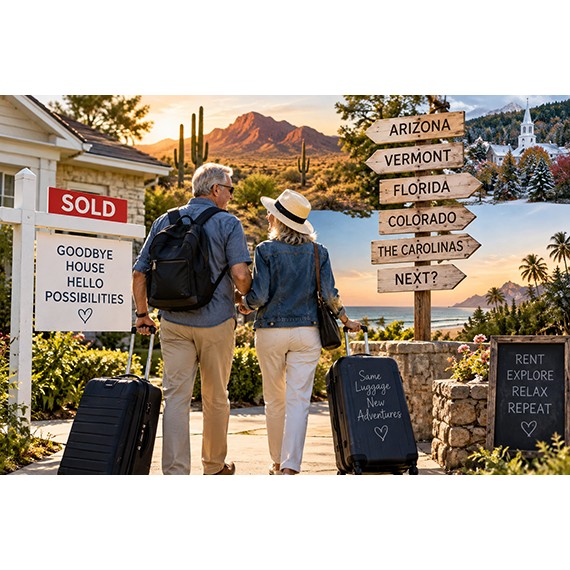
More retirees are starting to question whether they really need to own a home at all. Instead, some are selling, investing the proceeds, and renting—which gives them the ability to change where they live as their interests, family circumstances, and priorities change.
Always wondered what it would be like to live in Arizona? Go rent a place there for a year.
If you love the sunshine, desert scenery, and lack of snow shovels, stay.
If July rolls around and you decide that opening your front door feels remarkably similar to opening your oven, leave. You haven’t bought a house, paid thousands in closing costs, or committed yourself to living there for the next decade.
Try Colorado. Or the Carolinas. Or Montana. Or someplace you never imagined living until you had the freedom to try it.
Family can change the equation, too.
Suppose your daughter lives in Vermont and announces that your first grandchild is on the way. Suddenly, those beautiful Arizona sunsets might have some competition.
When you own a house, moving closer can be a major undertaking. When you rent, the conversation might simply be, “When does our lease end?”
And off to Vermont you go.
That is the part of this trend I find particularly interesting. Selling your house doesn’t necessarily mean you’re giving up your home. It means you no longer have a piece of real estate determining where home has to be.
There are some practical benefits, too. Homeownership comes with roofs, air conditioners, plumbing, landscaping, insurance, property taxes, and the uncanny ability of expensive things to break at precisely the wrong time.
When you rent, many of those problems become someone else’s problems.
Of course, there is another side to the equation.
Rent can increase. You give up potential appreciation on a home you no longer own. There can be tax considerations when selling, and your retirement plan needs to account for housing expenses that may continue for the rest of your life. Some people also simply like owning their home. They want roots, familiar neighbors, and the security of knowing exactly where they belong.
There is nothing wrong with that.
The point isn’t that retirees should sell their homes and rent. It’s that they shouldn’t automatically assume they shouldn’t.
For many people, their house is one of their largest assets. Selling it may unlock substantial equity that can be invested and used to support retirement. But the biggest benefit may not show up on a financial statement at all.
It’s flexibility.
Spend a year near the beach. Move closer to the grandchildren for a while. Try the mountains. Live in a walkable downtown. Head south for a couple of years and then change your mind.
After decades of structuring your life around jobs, schools, commutes, mortgages, and responsibilities, retirement may finally give you the opportunity to ask a very different question:
Where do we want to live next?
You don’t have to know the answer for the next 20 years. You only have to know the answer for now.
Before putting the “For Sale” sign in the yard, work with a CFP® professional to run the numbers and determine whether renting can provide the financial security—and the freedom—you want from retirement.
Published: October, 2026
TLP Financial Services, Inc. is a registered investment advisor